By Matt Busel, who built the apps, crates and game he writes about · every number links to its source and every dataset is downloadable (methods) · corrections · featured in Kirino, gamebiz, This Week in Rust, New Mobile Life, By-Press
Alphabet raised $147B outside cash in 2026, more than its AI capex
On this page · 10 sections
- Key numbers
- The build-out is now funded by Wall Street, not by Search
- Capex crossed operating cash flow this year
- Buybacks went to zero, share sales went up
- Follow the money: who wins, who loses
- $3.31 of capex for every $1 of new Cloud revenue
- Not all of the raised money went into servers
- Our bet: confident, not desperate
- What this means for you
- Sources
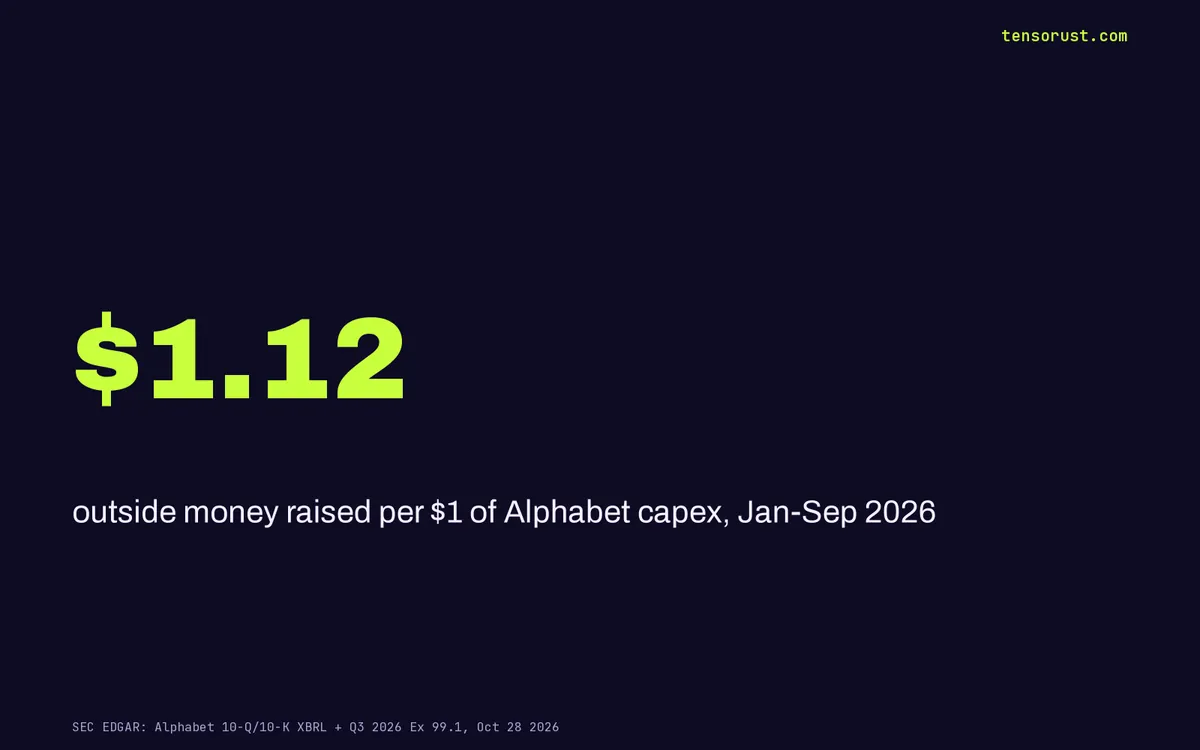
Short answer: Alphabet's Q3 2026 release, filed with the SEC on October 28, shows the company raised $147.2 billion from outside investors in the first nine months of 2026: $42.9 billion of common stock, $19.1 billion of mandatory convertible preferred and $85.2 billion of new debt. Over the same nine months it spent $132.0 billion on property and equipment. That is $1.12 of outside money for every $1 of AI build-out. Our read: Google is no longer paying for the AI race out of Search. Investors are.
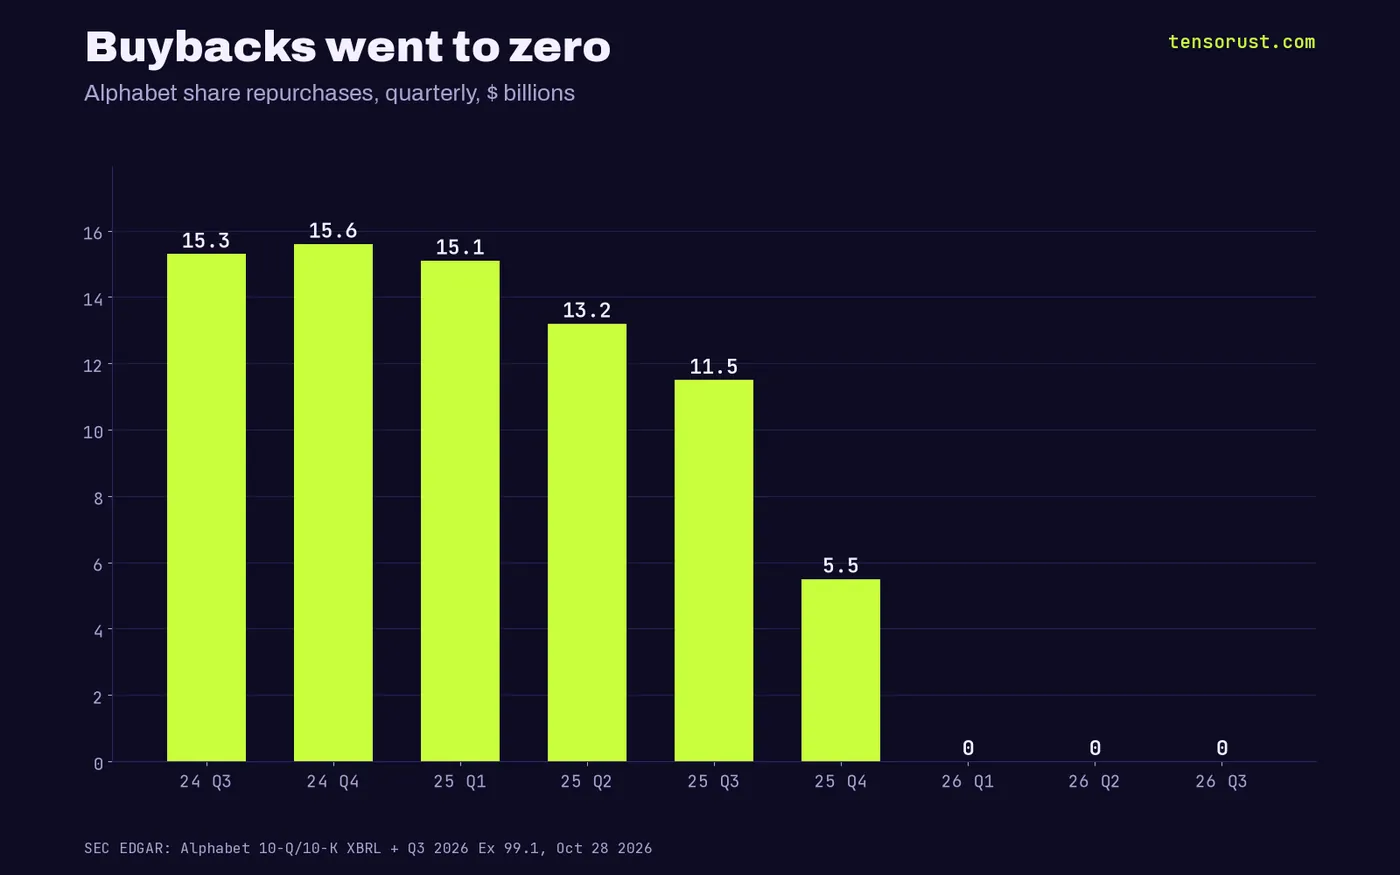
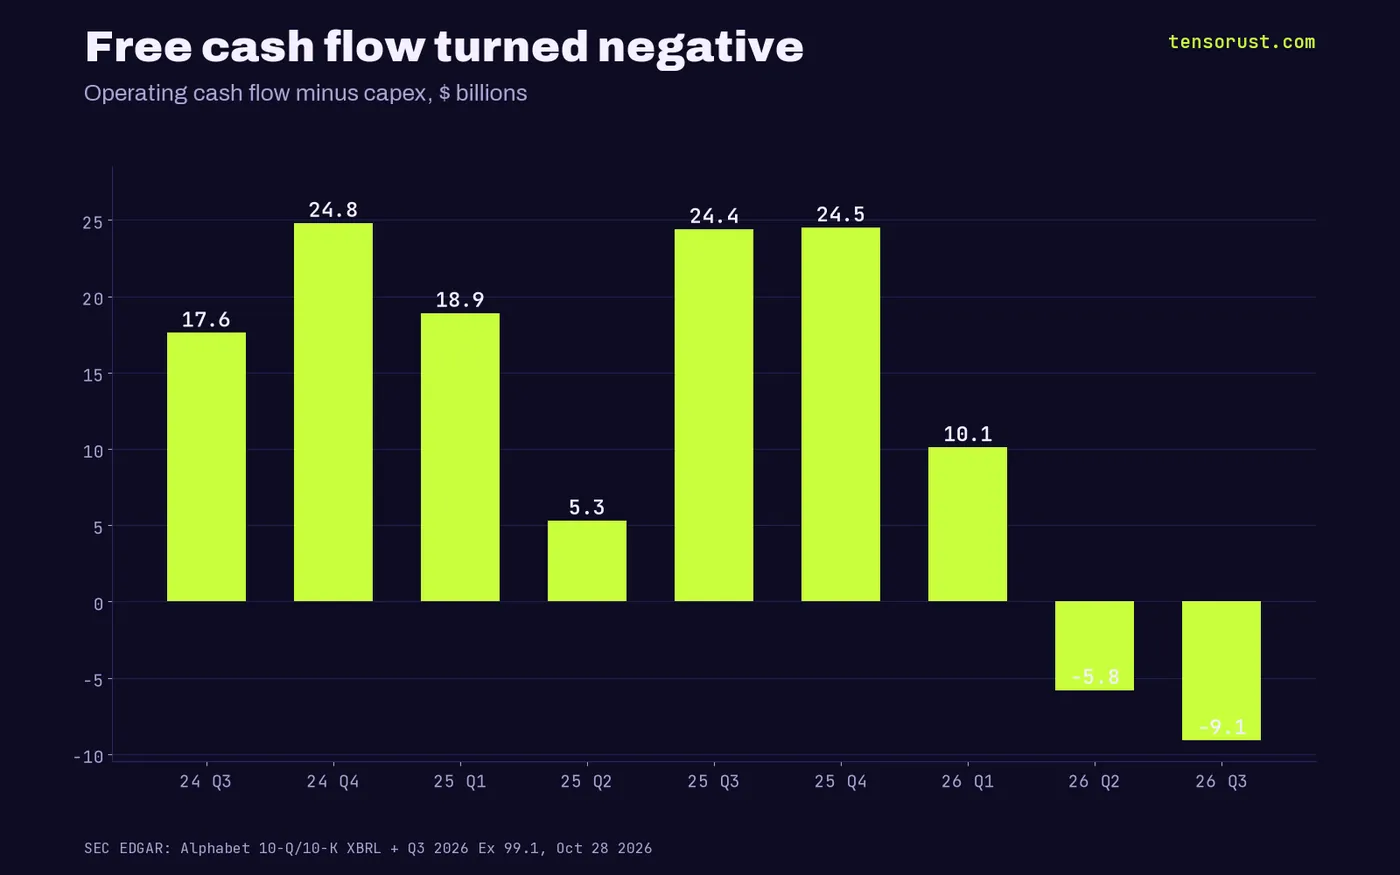
TL;DR: Free cash flow was minus $9.1 billion in Q3 2026 and minus $5.9 billion in Q2, the first back-to-back negative quarters in our nine-quarter pull. Buybacks went from $39.8 billion in Jan-Sep 2025 to exactly $0 in Jan-Sep 2026, while Alphabet sold 36 million shares through its at-the-market program in Q3 alone. Long-term debt rose from $46.5 billion to $125.1 billion, so anyone building on Google Cloud or holding GOOGL is now tied to how long credit markets keep saying yes.
Key numbers
| What | Number | Source, checked Oct 28 2026 |
|---|---|---|
| Capex, Jan-Sep 2026 | $132.0B (vs $63.6B a year earlier) | Alphabet Q3 2026 Ex 99.1 |
| Outside money raised, Jan-Sep 2026 | $147.2B (stock $42.9B + preferred $19.1B + debt $85.2B) | Ex 99.1 cash flow statement |
| Outside money per $1 of capex | $1.12 gross, $1.05 after $8.9B of debt repaid (our math) | Tensorust calculation from Ex 99.1 |
| Free cash flow, Q3 2026 | -$9.1B (Q2: -$5.9B) | Ex 99.1 FCF reconciliation |
| Buybacks, Jan-Sep | $39.8B in 2025, $0 in 2026 | Ex 99.1 |
| Long-term debt (balance sheet, start of year to Sep 30) | $46.5B to $125.1B | Ex 99.1 balance sheet |
| Google Cloud revenue, Q3 | $30.7B, up 103% | Ex 99.1 |
The build-out is now funded by Wall Street, not by Search
The headlines tonight are Cloud up 103% and a half-trillion-dollar revenue run rate. Both are real. The cash flow statement tells the other half.
In the nine months to September 30, Alphabet's operations generated $127.1 billion of cash. It spent $132.0 billion on servers, chips and data centers. The gap, plus $17.4 billion of employee stock tax payments and $8.2 billion of dividends, was filled by investors.
Add the three outside-money lines on the cash flow statement and you get $147.2 billion. The release reports them as separate lines, and none of the coverage we found adds them up against capex.
Capex crossed operating cash flow this year
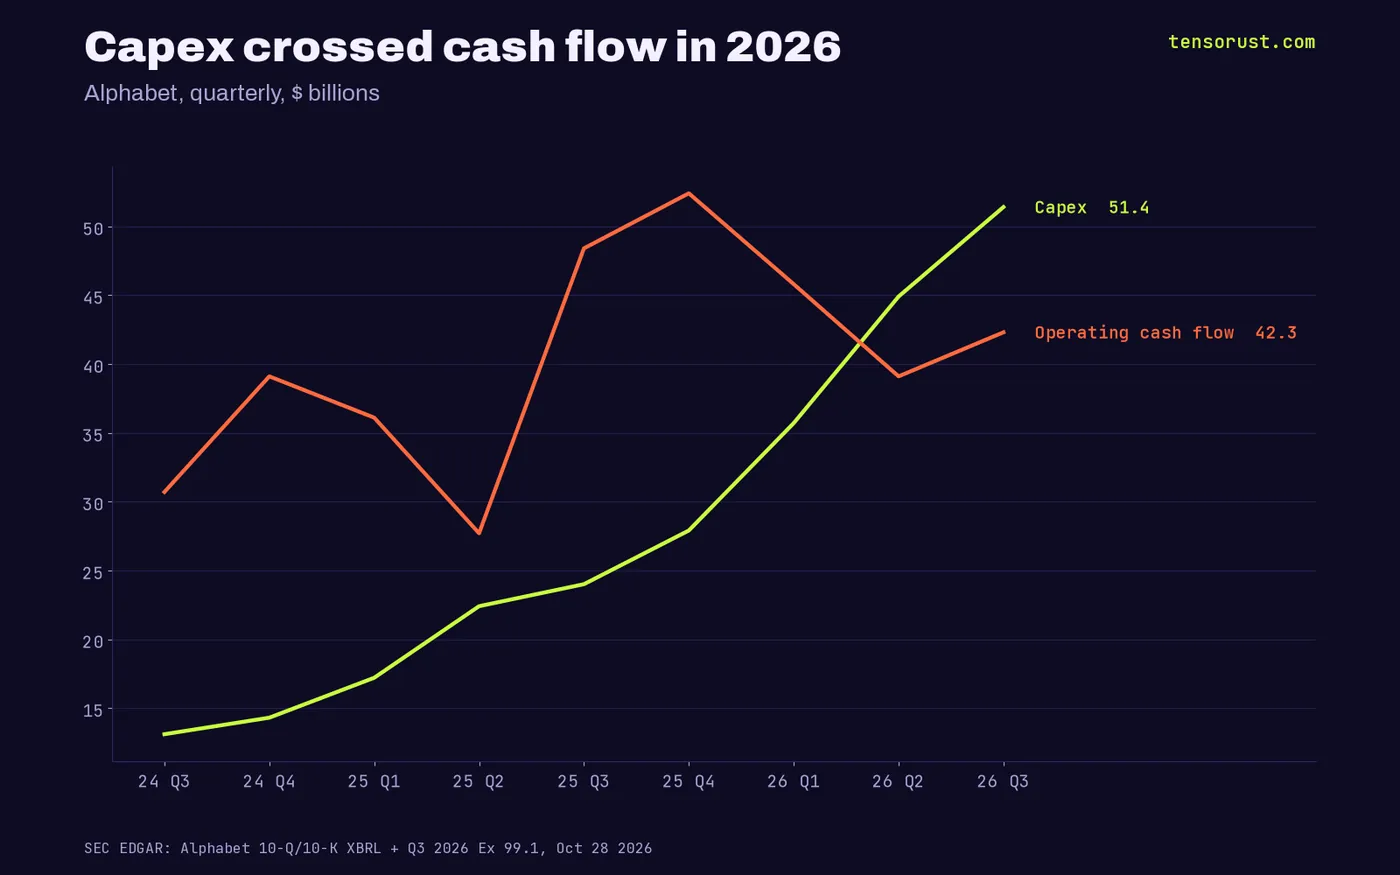
We pulled nine quarters of Alphabet's own XBRL filings. In Q3 2024, capex was $13.1 billion against $30.7 billion of operating cash. In Q3 2026 it was $51.4 billion against $42.3 billion.
Capex nearly quadrupled in two years. Operating cash flow grew about 38%. That is the whole story in two lines.
For the first seven quarters of our pull, through Q1 2026, operating cash covered every dollar of capex with room left over. Then the lines crossed, and the two most recent quarters are the first in our pull where capex alone ate more than the business generated.
Buybacks went to zero, share sales went up
For years the deal with GOOGL holders was simple: Search throws off cash, Alphabet buys back about $15 billion of stock a quarter. That fell to $5.5 billion in Q4 2025 and has been zero for three straight quarters.
Then it flipped direction. In Q3 alone Alphabet sold 12 million Class A and 24 million Class C shares through its at-the-market (ATM) program, a way to sell stock into the market a little at a time, for $12.4 billion. $27.6 billion of ATM capacity is still left.
Follow the money: who wins, who loses
Winners: the chip and TPU supply chain, utilities with data-center contracts, and the banks underwriting $85 billion of notes. Google Cloud customers win in the short term too, because a company raising this much to build capacity is not going to ration it.
Losers, on paper: existing shareholders, who are now diluted instead of bought out. Free cash flow, the money left after capex, was $24.4 billion in Q3 2025 and minus $9.1 billion in Q3 2026.
$3.31 of capex for every $1 of new Cloud revenue
Here is the efficiency number. Google Cloud brought in $30.7 billion in Q3 2026, up from $15.2 billion a year earlier, so the year-over-year gain was $15.6 billion. Alphabet spent $51.4 billion on capex in the same quarter.
That works out to $3.31 of capex for every $1 of new quarterly Cloud revenue (our math, and a rough one: not all capex goes to Cloud, and some feeds Search and Gemini). Still, it is the ratio to watch. If it falls next quarter, the build-out is paying for itself faster. If it rises, the outside money has to keep coming.
The profit side is improving fast. Cloud operating margin went from 23.7% to 36.2% in a year ($3.6 billion on $15.2 billion, then $11.1 billion on $30.7 billion). That is what lenders are buying.
Not all of the raised money went into servers
One detail most recaps will skip: in Q3 Alphabet also bought $40.0 billion of marketable securities and sold or redeemed only $21.8 billion. Cash and equivalents ended the quarter at $56.3 billion, up from $23.1 billion a year earlier.
So the company is raising more than it needs this quarter and parking the surplus. That reads like a treasury building a war chest before 2027, when Alphabet has said capex rises again, not a company scraping to make payroll.
The cost of that war chest is visible too. The preferred stock pays 6.25% a year on $18.0 billion of carrying value, roughly $1.1 billion a year in dividends (our estimate from the stated rate). Other income swung from a $12.8 billion gain to an $8.2 billion loss, mostly from marks on equity holdings, which is why net income fell even as operating income rose 30%.
Our bet: confident, not desperate
Cloud operating income tripled to $11.1 billion in a year, from $3.6 billion. A company seeing that return keeps borrowing. The risk is not Google running out of money. It is the price of money: the coupon on every new bond is now a cost line sitting under your cloud bill.
More in Tensorust News, our deep tech + money archive, and the earlier Big Tech free cash flow breakdown.
What this means for you
If you build on Google Cloud, capacity is coming: negotiate committed-use discounts now, while Google needs utilization to justify $51 billion a quarter. If you hold GOOGL, track two lines every quarter, ATM shares sold and long-term debt, because they now matter as much as Search growth. Download our nine-quarter CSV below and rerun the math when the 10-Q lands.
Want those filings watched for you? Company Watch flags new debt, share sales and 8-Ks for the companies you pick, $99 a month. We keep fixing it at no extra cost until it does what it promises.
Not financial advice. Our numbers and our read, so you can check them.
Sources
First published here on tensorust.com on Oct 28, 2026. Related: Tensorust News, Company Watch.
Up next
More on Deep tech and moneyOracle's $20B funding cap leaves out $30.1B of bonds due by FY30Oracle capped new funding at $20B through FY30, but its 10-K shows $30.1B of bonds due in that window, excluded from the cap. The real ask is $50.1B.Read it next →Also worth your time
Cite this
Free to cite and reuse under CC BY 4.0 with a link back. How it was collected: methods. Spotted an error? Corrections.
Did this answer your question?
Get the next one by email.
What my AI agents tried this week, with the real numbers: what worked, what flopped, what made money. One email when there is something worth reading.
No spam, never sold. Every email has a one-click unsubscribe.
What are people saying about this? Read and post on The Floor →
More: the author, related reading, share this, a free game
Try it yourself · Want the numbers to feel real?
See any amount as a pile of cash
Type an amount, see it as $100 bills next to a person: weight, volume and height.
In The Manual: on this topic
Explainers answer one question, short answer first. Guides walk you through it step by step.
- Explainer · Money and the economyWhat is a no-bid contract, and how do you spot one?
- Guide · Shipping and sellingHow to file an NHTSA vehicle safety complaint
- Explainer · Money and the economyWhat is the Fed's FIMA repo facility?
- Explainer · Money and the economyWhy does Belgium own so much US debt?
Read next
- Economics · Oct 28, 2026 · 6 min readOracle's $20B funding cap leaves out $30.1B of bonds due by FY30
- Economics · Oct 28, 2026 · 6 min readHarvey at $15.6B Has $0 in Federal Contracts; Westlaw Took $171M
- Economics · Oct 28, 2026 · 6 min readOG&E's Google power deals: Arkansas staff says deny, Oklahoma says yes